Economics & Policy
How Bad Is the National Debt?
What the debt figures measure, how the debt changed under each president, and what CBO projects next.
Economics & Policy
What Causes Inflation?
What drove the 9.1% peak of 2022 and the 2026 rise, and what the Fed did.
Economics & Policy
Is the Gender Wage Gap Real?
Why women earn less: discrimination, choice, hours, or all three?
Which Presidents Created the Most Jobs?
Claims about which president created the most jobs rest on one number: the change in payroll jobs between the start and the end of a term. This page gives that count for every president since 1939, says what it measures, and asks how much of it a president controls.
Jump to the verdict ↓
The short answer
Bill Clinton, if you count jobs added. Payroll jobs grew by 22.9 million over his two terms, more than under any other president since the figures begin in 1939. Joe Biden’s 15.4 million is the most for one four-year term. But the count says little about what a president did. A study of 1949 to 2013 found the economy grew faster under Democrats. It traced none of the gap to fiscal policy (taxes and government spending) or monetary policy (mainly the Federal Reserve setting short-term interest rates).
How a jobs number is counted
A president’s jobs number is the change in jobs between two months, and three choices move it: the survey, the months, and whether government jobs are counted.
The Bureau of Labor Statistics (BLS) runs two monthly surveys. Its payroll survey of employers counts jobs, so a person with two jobs is counted twice. It leaves out agricultural workers, the unincorporated self-employed, unpaid family workers and private household workers. The household survey includes them and counts each employed person once.
This page uses the payroll survey, which gives the monthly change in payroll jobs in BLS’s Employment Situation release. BLS says the two measures “track well over the long term” but that “periodic divergences occur”.
The months chosen also change the total. This page counts from the month each president took office to the month the term ended, so most terms run from January to January. Starting Barack Obama’s count at the payroll low of February 2010, instead of January 2009, adds 4.4 million jobs to it. Ending Donald Trump’s first-term count in February 2020, before the pandemic, turns a loss of 2.8 million into a gain of 6.7 million.
Government jobs are part of the total: 23.3 million in September 2026, 20.6 million of them in state and local government. Private and government jobs can move apart. Over Obama’s two terms, private payrolls grew by 11.8 million while government payrolls fell by 263,000.
A total also needs a yardstick: the monthly job gain that keeps the unemployment rate from rising or falling. Estimates of it swing with assumptions about immigration. Two economists at the Federal Reserve Bank of St. Louis put it at about 153,000 a month in April 2025. One of them, Alexander Bick, put it at 15,000 to 87,000 a month for 2026.
Unemployment rates and the employment-population ratio
The official unemployment rate, U-3, counts people who have no job, are available for work and looked for work in the past four weeks. It also counts people laid off temporarily who expect to be recalled. It gives them all as a share of the labor force.
BLS’s broadest rate, U-6, also counts people who want and are available for a job and have looked in the past year but not in the past four weeks. It adds people working part time for economic reasons, such as slack work or not finding a full-time job. In September 2026 U-3 was 4.2% and U-6 was 7.6%.
The employment-population ratio, the share of the civilian population aged 16 and over, outside institutions, that has a job, does not depend on whether people are looking. After the 2007–09 recession, U-3 fell from 10.0% in October 2009 to 4.7% in January 2017. Over the same years the ratio rose only from 58.5% to 59.9%.
Jobs added under each president
In the Bureau of Labor Statistics (BLS) payroll series, which begins in 1939, presidents’ totals run from a loss of 2.8 million jobs to a gain of 22.9 million. The loss came in Donald Trump’s first term, the only one that ended with fewer jobs than it began with. The 22.9 million came in Bill Clinton’s two terms, more than in any other presidency. Ronald Reagan’s 16.1 million and Joe Biden’s 15.4 million come next.
How to read it: each bar is the change in payroll jobs, in millions, from the month a president took office to the month the term ended. A bar below zero is a loss. Roosevelt’s bar starts in January 1939, when the series begins, and Trump’s second term runs to September 2026. The table below gives each value. Source: BLS, Current Employment Statistics, total nonfarm payrolls, seasonally adjusted (series PAYEMS in Federal Reserve Economic Data, or FRED).
| President | Months counted | Jobs added, millions | Per month, thousands | Change, % |
|---|---|---|---|---|
| Roosevelt (series from 1939) | Jan 1939–Apr 1945 | 11.5 | 154 | 38.5 |
| Truman | Apr 1945–Jan 1953 | 8.7 | 94 | 21.0 |
| Eisenhower | Jan 1953–Jan 1961 | 3.5 | 37 | 7.1 |
| Kennedy | Jan 1961–Nov 1963 | 3.6 | 105 | 6.7 |
| Johnson | Nov 1963–Jan 1969 | 12.2 | 197 | 21.3 |
| Nixon | Jan 1969–Aug 1974 | 9.2 | 137 | 13.2 |
| Ford | Aug 1974–Jan 1977 | 2.1 | 71 | 2.6 |
| Carter | Jan 1977–Jan 1981 | 10.3 | 215 | 12.8 |
| Reagan | Jan 1981–Jan 1989 | 16.1 | 168 | 17.7 |
| George H. W. Bush | Jan 1989–Jan 1993 | 2.6 | 55 | 2.5 |
| Clinton | Jan 1993–Jan 2001 | 22.9 | 239 | 20.9 |
| George W. Bush | Jan 2001–Jan 2009 | 1.4 | 14 | 1.0 |
| Obama | Jan 2009–Jan 2017 | 11.5 | 120 | 8.6 |
| Trump, first term | Jan 2017–Jan 2021 | −2.8 | −58 | −1.9 |
| Trump, first term to February 2020 | Jan 2017–Feb 2020 | 6.7 | 180 | 4.6 |
| Biden | Jan 2021–Jan 2025 | 15.4 | 321 | 10.8 |
| Trump, second term so far | Jan 2025–Sep 2026 | 0.8 | 39 | 0.5 |
As a share of the jobs that existed when they took office, though, Lyndon Johnson’s gain and Harry Truman’s were slightly larger than Clinton’s. Franklin Roosevelt’s 38.5% is larger, but it is counted from January 1939, when the series begins, not from when he took office.
Biden’s 15.4 million is the largest gain of any single four-year term in the series. The next largest is Clinton’s first term, at 11.6 million. Biden took office with payrolls 9.4 million below their February 2020 peak, and left with them 6.0 million above it.
Trump’s second term added 776,000 jobs in its first 20 months. That is 39,000 a month, the slowest pace of any presidency in the table without a recession so far. Government payrolls fell by 230,000 over those months. Over the same months the unemployment rate rose from 4.0% to 4.2%.
| President | Private jobs, millions | Government jobs, millions | Unemployment rate, start → end | Recessions in the term (NBER) |
|---|---|---|---|---|
| Reagan | 14.7 | 1.4 | 7.5% → 5.4% | Jul 1981–Nov 1982 |
| George H. W. Bush | 1.5 | 1.1 | 5.4% → 7.3% | Jul 1990–Mar 1991 |
| Clinton | 21.0 | 1.9 | 7.3% → 4.2% | None |
| George W. Bush | −0.4 | 1.7 | 4.2% → 7.8% | Mar–Nov 2001; Dec 2007–Jun 2009 |
| Obama | 11.8 | −0.3 | 7.8% → 4.7% | Dec 2007–Jun 2009, which began before the term |
| Trump, first term | −2.2 | −0.6 | 4.7% → 6.4% | Feb–Apr 2020 |
| Trump, first term to February 2020 | 6.1 | 0.5 | 4.7% → 3.5% | None |
| Biden | 13.6 | 1.8 | 6.4% → 4.0% | None |
| Trump, second term so far | 1.0 | −0.2 | 4.0% → 4.2% | None so far |
The yearly benchmark revision
Each year BLS benchmarks its payroll figures to comprehensive counts of employment drawn mainly from state unemployment insurance tax records, and the totals above can change with it. In August 2024 BLS put its preliminary revision to March 2024 employment at −818,000. The final revision, published in February 2025, was −598,000, not seasonally adjusted.
The preliminary revision to March 2025, published in September 2025, was −911,000, or 0.6% of jobs. Over the previous ten years the average size was 0.2%. The final figure, published on 11 February 2026, was −898,000 seasonally adjusted, or −861,000 not seasonally adjusted. It lowered the January 2025 level, which ends Biden’s count and starts Trump’s second term, by 785,000.
What a president controls
Three things limit what a president controls: policy acts with a delay, the Federal Reserve sets short-term interest rates, and shocks such as the pandemic strike whoever is in office.
Monetary policy acts slowly. Central bankers speak of its “long and variable lags”, a term coined by the economist Milton Friedman. Friedman found that monetary policy’s effect arrived between 4 and 29 months after a policy action, as a St. Louis Fed economist summarized his work in 2023. He found that range across 18 business cycles.
In the study described below, Alan Blinder and Mark Watson, economists at Princeton, allow for a delay before a new president can affect the economy. They charge the first quarter of each term to the president before.
The Federal Reserve (the Fed), not the president, sets short-term interest rates. Congress structured it to be “independent within the government”, the San Francisco Fed explains. Presidents appoint its seven governors with the Senate’s consent, but the appointments are staggered and the terms last 14 years.
For example, the recession that began six months into Ronald Reagan’s first term was triggered by tight monetary policy, aimed at inflation, after the federal funds rate approached 20 percent. It lasted from July 1981 to November 1982. Federal Reserve History records what happened when the Fed let the rate fall back to 9 percent. The unemployment rate dropped from nearly 11 percent at the end of 1982 to 8 percent a year later.
The pandemic shows how a shock can swamp a term. Payrolls fell by 21.9 million in March and April 2020, more than any president’s whole-term gain except Clinton’s.
What each president inherited
The three largest totals since 1981, Clinton’s, Reagan’s and Biden’s, all began with the unemployment rate above 6%.
Reagan’s total includes the 1981–82 recession and the recovery after it: payrolls grew 10.9% in the three years after the recession ended in November 1982. The unemployment rate fell from 7.5% when he took office to 5.4% when he left. He is the only Republican president since the rate’s series began in 1948 to leave it lower than he found it.
George H. W. Bush’s term included the recession of July 1990 to March 1991. In March 1991 Alan Greenspan, the Federal Reserve’s chairman, told Congress that the sudden rise in oil prices had made households cut back their spending in real terms. He added that tighter credit at banks and problems in real estate were holding back activity. Clinton had no recession; the next began in March 2001, two months into George W. Bush’s first term.
George W. Bush’s eight years included the recession of March to November 2001 and most of the one from December 2007 to June 2009. Those dates are the National Bureau of Economic Research’s. Private payrolls fell over the eight years. From December 2007 to February 2010 payrolls fell by 8.7 million, the largest fall in the number of jobs in the series until 2020. When Barack Obama took office in January 2009, they were falling by 768,000 a month.
The 2009 stimulus law was the American Recovery and Reinvestment Act. The Congressional Budget Office estimated that it raised the number of people employed by 1.4 million to 3.3 million in the second quarter of 2010. Even so, the recovery was slow: payrolls grew 2.3% in the three years after the recession ended in June 2009, against 10.9% after the 1982 recession ended.
From March 2010, private payrolls rose for 83 months in a row to January 2017, the longest run in the series to that point. State and local governments, by contrast, cut 747,000 jobs from July 2008 to July 2013 and had regained 449,000 by January 2017.
Donald Trump inherited an expansion. Payrolls grew by 180,000 a month from January 2017 to February 2020, slower than the 224,000 a month of Obama’s last three years. The unemployment rate fell to 3.5% in September 2019, the lowest since 1969, and the rates for Black and Hispanic workers reached record lows at the time. Then the pandemic struck, and payrolls ended his term 2.8 million below where they began.
Joe Biden took office during the recovery from the pandemic. In February 2021 the Congressional Budget Office projected that, without his proposed relief plan, employment would regain its pre-pandemic level in 2024. Payroll jobs passed it in June 2022, and the household survey’s count of employed people in August 2022. These figures cannot show how much of that faster recovery his American Rescue Plan caused. Prices rose faster than pay: average hourly earnings, adjusted for consumer prices, fell 2.1% in 2021 and 1.4% in 2022, December to December.
The strongest case for each party
Supporters of Republican policy argue that lower tax rates raise the after-tax return on investing and on working. They point to the expansion that began in November 1982 and lasted until July 1990, and to an unemployment rate of 3.5% in September 2019. Congress’s Joint Committee on Taxation, whose staff analyze tax bills, estimated that the 2017 tax law would raise gross domestic product (GDP) by about 0.7% on average over ten years. It put the rise in employment at about 0.6%, also on average over ten years.
But Reagan’s expansion followed a recession that tight monetary policy had triggered. And job growth under Trump before the pandemic was slower than in the three years before he took office. The Joint Committee on Taxation also estimated that the extra growth would bring in about $451 billion of revenue. That is less than a third of the $1,456 billion the law would otherwise cost over ten years.
The case for Democratic policySupporters of Democratic policy argue that consumer spending, about two-thirds of GDP, drives hiring, so policies that support incomes support jobs. The Democrats on Congress’s Joint Economic Committee wrote in October 2024 that job growth under the last seven presidents totaled over 50 million under Democrats. They put the total under Republicans at 17 million.
On current Bureau of Labor Statistics figures, with Biden’s term counted to its end in January 2025, those totals are 49.9 million and 17.4 million, so the gap holds. But Alan Blinder and Mark Watson, in the study described below, found that fiscal and monetary policy did not explain the faster growth under Democratic presidents.
What Blinder and Watson found
Alan Blinder and Mark Watson, economists at Princeton, published a study of economic performance under Democratic and Republican presidents in the American Economic Review in 2016. It covers the 16 presidential terms from Harry Truman’s elected term to Barack Obama’s first, so it ends before Trump and Biden took office.
| Measure | Democrats | Republicans |
|---|---|---|
| Real gross domestic product (GDP) growth, % | 4.33 | 2.54 |
| Payroll job growth, % | 2.59 | 1.17 |
| Household survey job growth, % | 1.76 | 1.20 |
| Change in the unemployment rate over a term, points | −0.83 | +1.09 |
The gaps in GDP growth, payroll job growth and the change in the unemployment rate are statistically significant; the smaller gap in the household survey’s count is not. A significant gap is one that, by the usual test, is unlikely to arise by chance.
In their analysis, Blinder and Watson attribute none of the faster growth under Democratic presidents to fiscal or monetary policy. In their abstract, they write that “it appears that the Democratic edge stems mainly from more benign oil shocks, superior total factor productivity (TFP) performance, a more favorable international environment, and perhaps more optimistic consumer expectations about the near-term future”.
Their conclusion lists oil shocks, productivity, defense spending (if the Korean War is counted) and, more tenuously, growth abroad. Over the whole period, these explain up to 56 percent of the gap in GDP growth. Blinder and Watson add that “the rest remains, for now, a mystery”. They write that some, maybe all, of these factors “might be considered blends of good policy and good luck”.
The verdict: what the evidence shows
Bill Clinton, on the usual count. His eight years added 22.9 million payroll jobs, the largest gain under any president since the Bureau of Labor Statistics (BLS) payroll series began in 1939. Biden’s 15.4 million is the largest in a single term. The order changes with the measure. As a share of the jobs that existed when they took office, Johnson’s and Truman’s gains were slightly larger than Clinton’s. Counted only to February 2020, Trump’s first term shows a gain of 6.7 million.
The totals record what happened during each term more than what each president did. A policy’s effects arrive with a delay, short-term interest rates are the Federal Reserve’s to set, and the pandemic cut 21.9 million jobs in two months. Blinder and Watson’s study of 1949 to 2013 found faster growth under Democrats but attributed none of it to fiscal or monetary policy.
Four common claims, against the evidence
Claim“Biden created more jobs than any president in history”
Partly trueBiden’s 15.4 million is the largest gain in one four-year term since 1939, but Clinton’s two terms added 22.9 million. Biden took office with payrolls 9.4 million below their pre-pandemic peak.
Claim“Trump had the best economy ever before COVID”
Not on jobsPayrolls grew by 180,000 a month from January 2017 to February 2020, slower than the 224,000 a month of Obama’s last three years. The unemployment rate did fall to 3.5%, the lowest since 1969.
Claim“Trump lost 2.7 million jobs”
True, but incompleteOn current Bureau of Labor Statistics figures, payrolls ended his first term 2.8 million lower than they began. They had grown by 6.7 million before the pandemic, which took 21.9 million jobs in March and April 2020.
Claim“Democrats have a better jobs record. Proof their policies work better”
Record yes, proof noIn Blinder and Watson’s study of 1949 to 2013, payroll jobs grew 2.59% a year under Democrats and 1.17% under Republicans. They attributed none of the faster economic growth under Democrats to fiscal or monetary policy.
Download the conclusion
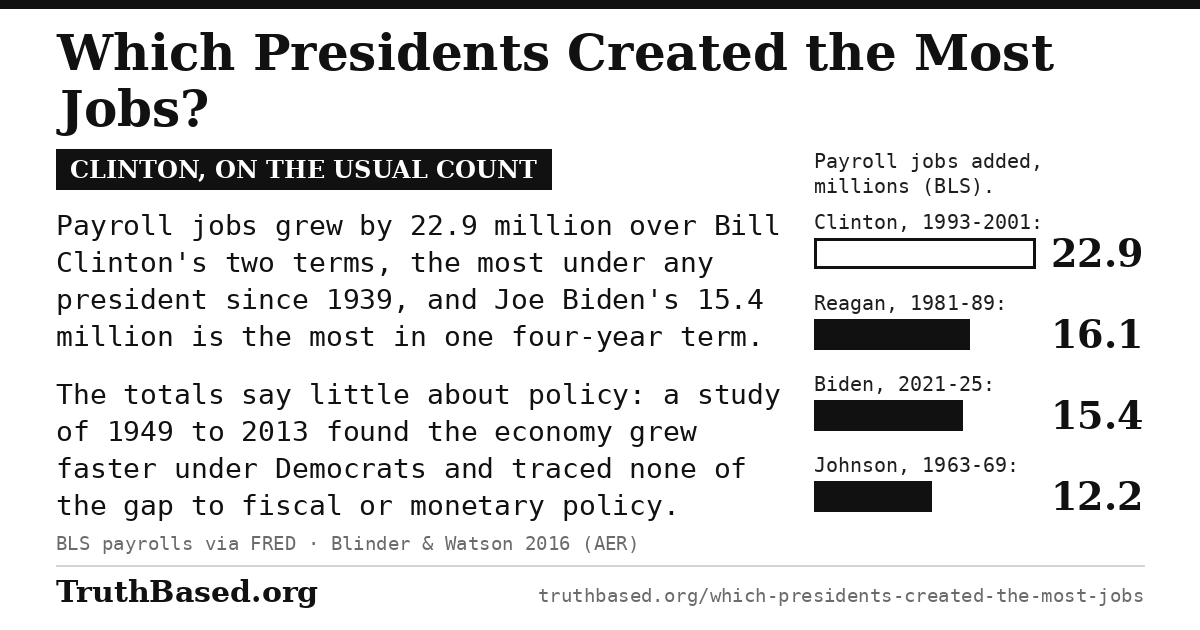
The verdict above as one image, with bars for the four largest gains in payroll jobs under a president since 1939. Clinton’s was 22.9 million and Reagan’s 16.1 million. Biden’s was 15.4 million and Johnson’s 12.2 million. The image is 1,200 by 630 pixels, the size social networks use for link previews, and anyone may download it and post it.
What would change this conclusion
This article concludes that: (1) counted from the month each president took office to the month the term ended, Bureau of Labor Statistics (BLS) payroll figures show the largest gain since 1939 under Clinton, 22.9 million over two terms, and the largest in one four-year term under Biden, 15.4 million; (2) the order changes with the measure and the months counted; (3) Blinder and Watson found faster growth under Democrats from 1949 to 2013 that fiscal and monetary policy did not explain.
These conclusions would be falsified by:
• BLS revisions to the payroll series large enough to change which totals are largest; Clinton’s terms lead Reagan’s by 6.8 million, and Biden’s term leads Clinton’s first by 3.8 million
• A replication of Blinder and Watson’s study, extended to the terms since 2013, that finds fiscal or monetary policy explains much of the gap between the parties
• Studies of laws such as the 2017 tax law or the 2021 American Rescue Plan finding effects on payroll jobs large enough to explain most of a president’s total
Sources
U.S. Bureau of Labor Statistics. Current Employment Statistics (CES), national. Source for payroll jobs, total, private and government, by month since 1939, the series every total on this page is computed from, and the September 2026 figures. bls.gov/ces
Federal Reserve Bank of St. Louis. FRED: All Employees, Total Nonfarm (PAYEMS), with the series USPRIV, USGOVT, CES9092000001, CES9093000001, UNRATE, U6RATE, EMRATIO, CE16OV, LNS14000006, LNS14000009, CES0500000003, CPIAUCSL, PCE and GDP. The series as FRED distributes them, with job and unemployment data to September 2026. Source for every total, monthly pace and share in the tables and chart, the unemployment rates, the employment-population ratio, the run of private job gains, real average hourly earnings, and consumer spending as a share of GDP. fred.stlouisfed.org
U.S. Bureau of Labor Statistics. Labor Force Statistics from the Current Population Survey, and its concepts and definitions. Source for the household survey and the definitions of the unemployed and of the employment-population ratio. bls.gov/cps | definitions
U.S. Bureau of Labor Statistics. Comparing employment from the BLS household and payroll surveys. Last modified February 11, 2026. Source for what each survey counts and BLS’s statement that the two track well over the long term while periodic divergences occur. bls.gov
U.S. Bureau of Labor Statistics. The Employment Situation, Table A-15: Alternative measures of labor underutilization. Source for the definitions of U-3 and U-6 and their September 2026 values, 4.2% and 7.6%. bls.gov
U.S. Bureau of Labor Statistics. 2024 Preliminary Benchmark Revision. August 21, 2024. Source for the preliminary revision of −818,000 to March 2024 employment. bls.gov
U.S. Bureau of Labor Statistics. CES Benchmark Announcement: Revisions to total nonfarm employment. February 7, 2025. Source for the final revision of −598,000 to March 2024 employment, not seasonally adjusted. bls.gov
U.S. Bureau of Labor Statistics. Current Employment Statistics Preliminary Benchmark (National) news release. September 9, 2025. Source for the preliminary revision of −911,000 (−0.6%) to March 2025 employment, the 0.2% average size of the previous ten years’ revisions, and the benchmark to counts drawn mainly from state unemployment insurance tax records. bls.gov
Battista V, Khan R. BLS Establishment Survey National Estimates Revised to Incorporate March 2025 Benchmarks (CES National Benchmark Article). U.S. Bureau of Labor Statistics, February 11, 2026. Source for the final revision of −898,000 to March 2025 employment, seasonally adjusted (−861,000 not seasonally adjusted), and the revision of −785,000 to the January 2025 level. bls.gov
National Bureau of Economic Research. US Business Cycle Expansions and Contractions. Source for every recession date and for the expansions that began in November 1982 and June 2009. nber.org
Blinder AS, Watson MW. Presidents and the US Economy: An Econometric Exploration. American Economic Review, 2016;106(4):1015–1045. Source for the 16 terms from 1949 to early 2013, the figures in the table of Democratic and Republican terms and their statistical significance, the first quarter charged to the previous president, the sentence quoted from the abstract, the factors that explain up to 56 percent of the gap, and the authors’ words on the rest and on “good policy and good luck”. The 2014 working paper gives 4.35% for growth under Democrats; the published article gives 4.33%. aeaweb.org | NBER Working Paper 20324
Congressional Budget Office. Estimated Impact of the American Recovery and Reinvestment Act on Employment and Economic Output From April 2010 Through June 2010. August 24, 2010. Source for the estimate that the law raised the number of people employed by 1.4 million to 3.3 million in the second quarter of 2010. cbo.gov
Congressional Budget Office. An Overview of the Economic Outlook: 2021 to 2031. February 1, 2021. Source for the projection, made without the proposed relief plan, that employment would return to its pre-pandemic level in 2024. cbo.gov
Joint Committee on Taxation. Macroeconomic Analysis of the Conference Agreement for H.R. 1, the “Tax Cuts and Jobs Act”. JCX-69-17, December 22, 2017. Prepared by the committee’s staff. Source for the staff’s analysis of the law and the estimates that the law would raise GDP by about 0.7% and employment by about 0.6% on average over ten years, and bring in about $451 billion of revenue against a conventional cost of $1,456 billion. The committee is a joint committee of Congress under 26 U.S.C. 8001. jct.gov | 26 U.S.C. 8001
Sablik T. Recession of 1981–82. Federal Reserve History, November 22, 2013. Source for the recession’s trigger and dates, the federal funds rate approaching 20 percent, and the fall in unemployment after the Fed let the rate drop to 9 percent. federalreservehistory.org
Greenspan A. Statement before the Joint Economic Committee, U.S. Congress, March 13, 1991. Source for the Fed chairman’s account of the oil price rise, the restraint on credit at banks and the problems in real estate during the 1990–91 recession. fraser.stlouisfed.org
Dupor B. Examining Long and Variable Lags in Monetary Policy. Federal Reserve Bank of St. Louis, Regional Economist, May 24, 2023. Source for the term “long and variable lags”, coined by the economist Milton Friedman and prominent in how central bankers talk about monetary policy, and for Friedman’s finding of lags of 4 to 29 months across 18 business cycles. stlouisfed.org
Bick A. Breakeven Employment Growth: Estimate Range Widens in 2026. Federal Reserve Bank of St. Louis, On the Economy, March 24, 2026. Source for the definition of breakeven employment growth and the estimates of about 153,000 a month in April 2025 and 15,000 to 87,000 a month for 2026. stlouisfed.org
Federal Reserve Bank of San Francisco. U.S. Monetary Policy: An Introduction, Part 1. FRBSF Economic Letter 2004-01, January 16, 2004. Source for what fiscal and monetary policy are, the Fed’s independence within the government and the appointment of its governors to staggered 14-year terms. frbsf.org
Joint Economic Committee Democrats. The U.S. Economy Performs Better Under Democratic Presidents. October 7, 2024. Source for the committee’s count of job growth under the last seven presidents, over 50 million under Democrats and 17 million under Republicans. jec.senate.gov
Cite this article
TruthBased.org. “Which Presidents Created the Most Jobs?” Updated November 2026. https://www.truthbased.org/which-presidents-created-the-most-jobs