Economics & Policy
Where Does U.S. Federal Spending Go?
Where the $7.4 trillion of fiscal 2026 goes, and why interest now costs more than defense.
Economics & Policy
What Causes Inflation?
CPI and PCE data on what drove inflation from 2021, and what the Federal Reserve did.
Economics & Policy
Do Tariffs Bring Back Manufacturing Jobs?
Steel, tire and China tariffs and the 2025 escalation, measured by jobs saved and lost, cost per job and consumer impact.
How Bad Is the National Debt?
The federal debt passed $40 trillion in August 2026. This page sets out what the debt figures measure and how the debt changed under each president from Reagan to Biden. It then gives each party’s strongest case and what official projections say comes next.
Jump to the verdict ↓
The short answer
Serious, and getting worse. Debt held by the public, what the government owes to lenders outside it, is now about as large as the whole economy. Under current law, the Congressional Budget Office (CBO) projects it to pass its 1946 record and reach 175% of gross domestic product (GDP) by 2056. Net interest on the debt already costs more than defense. Both parties built it: measured against the economy, the debt rose under every president from Reagan to Biden except Clinton.
What the debt figures measure
The national debt can be counted in several ways, and each gives a different picture of the same borrowing.
The deficit is the gap in a single fiscal year between what the federal government spends and what it collects. The debt is the borrowing that covers those gaps, accumulated over the nation’s history, with the interest owed on it. So a president can shrink the deficit and still add to the debt, because any deficit, even a smaller one, is new borrowing.
Gross debt counts all of it, including the Treasury securities held by federal trust funds such as Social Security’s. That part is the government owing itself. Debt held by the public is what the government owes to lenders outside it, including the Federal Reserve, foreign investors and Americans. On September 30, 2026, the Treasury put gross debt at $40.2 trillion and debt held by the public at $32.4 trillion.
In 1998 the General Accounting Office described debt held by the public as the measure that “best represents the cumulative effect of past federal borrowing on the economy”. The office is now called the Government Accountability Office.
Debt is also measured against the size of the economy, as a share of gross domestic product (GDP). That is how the Congressional Budget Office (CBO) and the International Monetary Fund report it, and it lets years and countries of different size be compared. Suppose a $30 trillion economy adds $1 trillion of debt. That is a smaller burden than a $5 trillion economy adding $500 billion. A president can therefore add a lot of debt in dollars while the debt ratio falls, if the economy grows faster than the debt.
Mandatory and discretionary spending
Mandatory spending, such as Social Security, Medicare and Medicaid, is set by existing law and needs no yearly vote in Congress. Discretionary spending, including defense, is approved each year in appropriations bills. Net interest on the debt is counted separately from both. In fiscal year 2025, mandatory spending and net interest together came to $5.1 trillion. That was about 73% of the $7.0 trillion the government spent. Most of the budget therefore runs under laws already on the books unless Congress changes them.
The debt limit caps how much the Treasury may borrow to pay for spending and tax laws that Congress has already passed. In the Treasury’s words, it “does not authorize new spending commitments”. Congress has raised, extended, suspended or redefined it 90 times since 1960. Of those, 53 were under Republican presidents and 37 under Democratic ones.
The record by administration
Of the presidents from Reagan to Biden, Clinton is the only one under whom gross debt fell as a share of the economy, by 9.4 points over eight years. Debt held by the public also fell under Clinton alone, by 16.4 points. The table below follows each president from the end of the fiscal year in which he took office to the end of the fiscal year in which his successor did. Its figures come from the historical tables of the Office of Management and Budget (OMB).
The table also notes which party held Congress, because Congress passes the spending and tax laws a president signs. Fiscal year 2009 began under G.W. Bush and counts in his row, though the bank rescue (Troubled Asset Relief Program) and the Recovery Act both became law in it.
| Administration | Start, % of GDP | End, % of GDP | Change, points | Change in dollars, debt held by the public | Average yearly deficit | Congress |
|---|---|---|---|---|---|---|
| Reagan (1981–89) | 31.8% | 51.6% | +19.8 | +$1.4T | 4.2% GDP | Dem House entire term; GOP Senate ’81–’87 |
| G.H.W. Bush (1989–93) | 51.6% | 64.2% | +12.6 | +$1.1T | 4.1% GDP | Dem House & Senate |
| Clinton (1993–01) | 64.2% | 54.8% | −9.4 | +$0.1T | 0.1% GDP (surpluses in fiscal 1998–2001) | Dem ’93–’95; GOP Congress ’95–’01 |
| G.W. Bush (2001–09) | 54.8% | 82.1% | +27.3 | +$4.2T | 3.3% GDP | GOP House ’01–’07; GOP Senate except mid-’01 to late ’02; Dem Congress ’07–’09 |
| Obama (2009–17) | 82.1% | 104.3% | +22.2 | +$7.1T | 5.0% GDP | Dem unified ’09–’11; divided/GOP thereafter |
| Trump I (2017–21) | 104.3% | 123.2% | +18.9 | +$7.6T | 8.7% GDP | GOP unified ’17–’19; Dem House ’19–’21 |
| Biden (2021–25) | 123.2% | 123.3% | +0.1 | +$7.9T | 5.9% GDP | Dem unified ’21–’23; divided ’23–’25 |
Under Clinton, federal revenue rose from 17.0% of GDP in 1993 to 20.0% in 2000, the highest share since 1944. Defense spending fell from 4.3% of GDP to 2.9% over the same years. His own party held Congress for his first two years, and the Republicans held it for his last six.
Under Biden the debt ratio rose by 0.1 point, the smallest increase in the table, because GDP in current dollars grew almost as fast as the debt. The deficit still stayed above 5% of GDP in each of his four budget years. In dollars, the debt grew under every president in the table, so the useful comparison is with the size of the economy.
What presidents and Congress control
A president’s first budget takes effect only on October 1 of the inauguration year, when the term’s second fiscal year begins. Until then, for about eight months, the government is in a fiscal year that began under the previous president. Congress can still pass spending laws for that year after the inauguration, as it did in 2009, 2017 and 2025. The fiscal 2025 deficit of $1.8 trillion, for example, covers a year that began on October 1, 2024. Trump’s second term began on January 20, 2025.
Much of the rest of the budget is inherited too. Social Security, Medicare, Medicaid and interest payments continue under existing law without any new vote. In projections by the Congressional Budget Office (CBO), spending on Social Security and Medicare grows faster than the economy over the next ten years.
Presidents also inherit wars and recessions. Brown University’s Costs of War project puts the cost of the wars that followed September 11, 2001, at about $8 trillion, not counting future interest. Obama inherited both the Iraq and Afghanistan wars. By the National Bureau of Economic Research’s dates, G.W. Bush took office two months before the 2001 recession began, and Obama during the 2007–09 recession. The 2020 recession began in Trump’s last year, and Biden took office nine months after it ended.
Interest is owed on whatever debt a president inherits. Net interest doubled as a share of gross domestic product (GDP) between fiscal 2020 and 2025, from 1.6% to 3.2%, just above its previous peak in 1991. In fiscal 2025 it cost $970 billion, more than the $916 billion spent on defense. Medicare, at $997 billion, still cost slightly more.
Congress writes the laws that set spending and taxes. The Constitution says that “No Money shall be drawn from the Treasury, but in Consequence of Appropriations made by Law”. The Senate votes on the major fiscal laws of the last 25 years show how far each one was a single party’s.
Major fiscal laws and how the parties voted
Senate roll calls, with the House where a party gave no votes
2001 and 2003 Bush tax cuts2001: 58–33, with 12 Democrats for. 2003: 50–50, passed on the Vice President’s vote, with 2 Democrats for.
2008 bank rescue (Troubled Asset Relief Program)74–25, with most senators of both parties for.
2009 Recovery Act (Obama stimulus)60–38, with 3 Republicans for.
2017 tax act (Tax Cuts and Jobs Act, TCJA)No Democratic votes in either chamber; passed by reconciliation, a fast-track budget process in which Senate debate is limited, so reaching a final vote needs no three-fifths majority. Conventional cost, before any effect on the size of the economy, estimated by the Joint Committee on Taxation (JCT): $1.456 trillion over 2018–2027.
2020 Coronavirus Aid, Relief, and Economic Security (CARES) Act96–0.
2021 American Rescue PlanNo Republican votes in either chamber.
2021 Infrastructure Act69–30, with 19 Republicans for.
The strongest case on each side
The strongest Republican case is that the long-run problem is spending, not revenue. Revenue has averaged 17.3% of gross domestic product (GDP) over the past 50 years. The Congressional Budget Office (CBO) projects 17.8% in 2036. Spending has averaged 21.2% of GDP and is projected to reach 24.4% in 2036. CBO puts that rise down to Social Security, Medicare and net interest, partly offset by falling discretionary spending.
Republicans also point to the deficits of fiscal 2009, at 9.8% of GDP, and fiscal 2010, at 8.7%. Since 1930, only the Second World War and the pandemic years 2020 and 2021 saw larger ones. Democrats held Congress in both years and the White House from January 2009, though fiscal 2009 began under G.W. Bush.
Republicans can also point to the 2009 Recovery Act, which drew three Republican votes in the Senate, and the 2021 American Rescue Plan, which drew none. They can point as well to the Affordable Care Act, passed in 2010, which expanded Medicaid and created premium tax credits.
On taxes, the strongest case is not that tax cuts pay for themselves, which the official estimates of the 2017 act contradict. It is that lower rates raise investment and growth, which wins back part of the lost revenue.
The Joint Committee on Taxation (JCT) put the act’s conventional cost, before any effect on the size of the economy, at $1.456 trillion over 2018 to 2027. It found the act would raise GDP by about 0.7% on average over those years. That growth would win back $451 billion in revenue, less $66 billion in extra interest. The net $385 billion recovers about a quarter of the cost.
The strongest Democratic case is that tax choices built the debt as well. The Tax Foundation, a nonprofit tax policy research group, read a 2011 CBO review as showing what the Bush tax cuts of 2001, 2003 and 2004 cost. By its reading, they added about $1.8 trillion to deficits over 2002 to 2011, interest included.
The Committee for a Responsible Federal Budget is a nonprofit whose leaders include former heads of CBO and of the House and Senate budget committees. It estimates, from a 2025 CBO analysis, that extending the 2017 tax cuts would add about $37 trillion to the debt by 2054. As that group reports it, CBO found the extension would add to growth at first, start to subtract from it in 2028 and leave the economy smaller from 2034.
Democrats also note that Clinton’s 1993 budget act passed with no Republican votes and added income tax brackets of 36% and 39.6%. Deficits then fell every year to 1997. Surpluses followed in fiscal 1998 to 2001, the only ones since 1969.
In 2013 two economists at the International Monetary Fund, Olivier Blanchard and Daniel Leigh, studied plans to cut deficits during the crisis, which they date from 2009. Their main sample was the plans of 26 European economies for 2010 and 2011. In advanced economies, they found, “stronger planned fiscal consolidation has been associated with lower growth than expected”. They read this as fiscal multipliers, the effect of budget changes on output, being substantially higher than forecasters had assumed.
Conservative overclaim
“Obama doubled the debt.” During his presidency, debt held by the public more than doubled, from $6.3 trillion to $14.4 trillion. Gross debt rose from $10.6 trillion to $19.9 trillion, short of double. He took office during the longest recession since the Second World War, and fiscal 2009, which began almost four months earlier, ended with a $1.4 trillion deficit. By the Office of Management and Budget’s ratio, gross debt rose 22.2 points of GDP under Obama, against 27.3 under G.W. Bush over the same span of eight years. Trump’s first term added 18.9 points in four years. Debt held by the public rose more under Obama than under G.W. Bush, 23.5 points against 20.7.
Progressive overclaim
“Republican tax cuts caused the entire debt.” Tax cuts added trillions, but in dollars the debt rose under every president from Reagan to Biden. Recessions, wars and spending laws passed by both parties added to it too. CBO puts most of the coming rise in spending down to net interest, Social Security and Medicare.
Download this conclusion: did Obama double the debt?
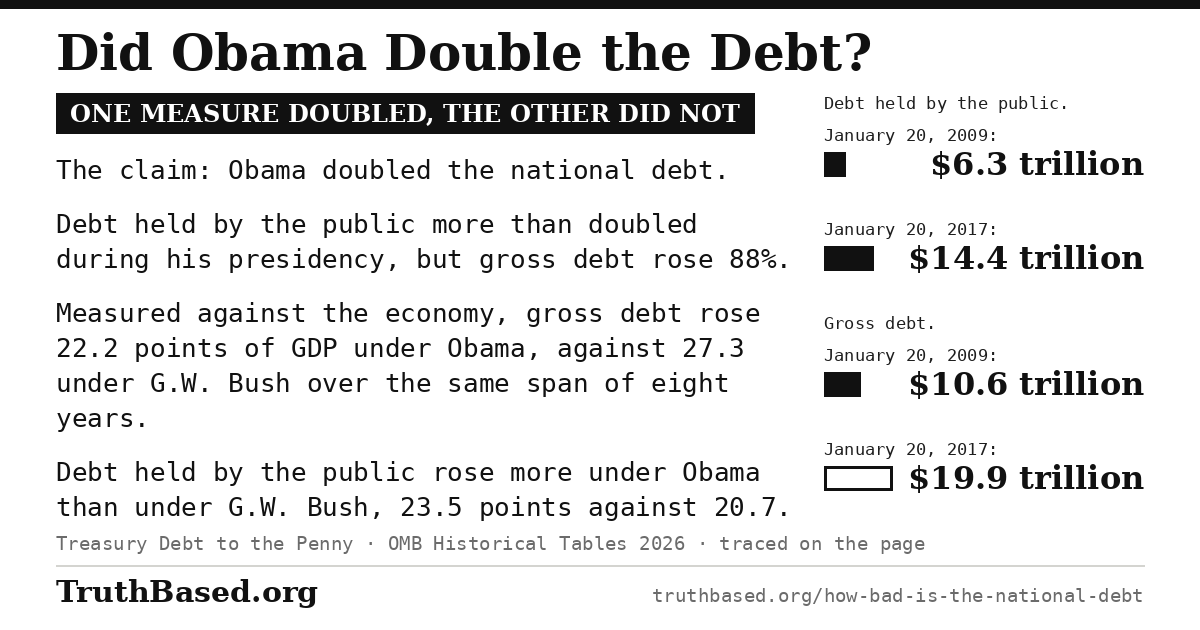
This card takes apart the claim that Obama doubled the national debt. It shows debt held by the public on the days he took office and left, $6.3 trillion and $14.4 trillion. It also shows gross debt on those days, $10.6 trillion and $19.9 trillion. It is 1,200 by 630 pixels, and anyone may download it and post it.
Where the debt is heading
Debt held by the public is already about double its average over the past 50 years, which was 51.2% of gross domestic product (GDP). Under current law, the Congressional Budget Office (CBO) projects it to rise every year, from 101% of GDP in 2026 to 120% in 2036. That would be higher than at any point in the nation’s history, above the record of 106% set in 1946. It would keep rising after that, and over the following two decades it would reach 175%.
How to read it: each bar is federal debt held by the public as a percentage of GDP. Three bars are history: the 1946 record, the average over 1976 to 2025, and 2025. Two are CBO’s projections under current law, for 2036 and 2056. The table below gives each value. Source: CBO, The Budget and Economic Outlook: 2026 to 2036, as presented in testimony on March 11, 2026.
| Year | Debt held by the public, % of GDP |
|---|---|
| 1946, the record | 106 |
| Average, 1976–2025 | 51.2 |
| 2025 | 99.4 |
| 2036, projected | 120.2 |
| 2056, projected | 175 |
In CBO’s projections, the deficit grows from $1.9 trillion in 2026 to $3.1 trillion in 2036. As a share of GDP it rises from 5.8% to 6.7%. The average over the past 50 years was 3.8% of GDP.
Net interest grows fastest of the main parts of the budget in CBO’s projections. It roughly doubles, from $1.0 trillion in 2026 to $2.1 trillion in 2036. By then it equals 4.6% of GDP.
The debt counts only what has already been borrowed. The Treasury’s Financial Report for fiscal 2025 projects that, under current policy, spending other than interest will exceed receipts over the next 75 years by $79.6 trillion in present value. Present value counts a future dollar as worth less than a dollar today, which could be invested and earn interest. The report concludes that the projected rise in the debt ratio means “current policy is unsustainable”. Its balance sheet shows $6.1 trillion of assets against $47.8 trillion of liabilities.
Whether debt this high slows growth is disputed. In 2010 Carmen Reinhart and Kenneth Rogoff reported on growth in 20 advanced economies after the Second World War. When public debt was above 90% of GDP, they found, growth averaged −0.1%. Three economists who rechecked the work later wrote that it gave “significant support for the austerity agenda” in Europe and the United States.
Those economists, Thomas Herndon, Michael Ash and Robert Pollin, found coding errors, selective exclusion of available data and unconventional weighting in it. Corrected, average real growth in those economies was 2.2% when debt was above 90% of GDP. Reinhart and Rogoff acknowledged the coding error but said it did not affect their paper’s “central message” in any significant way. They disputed the charges of selective exclusion and unconventional weighting.
Measured against their economies, some countries carry more debt than the United States. By the International Monetary Fund’s figures, Japan’s gross government debt has been above 200% of its GDP since 2013. By the same measure, the United States’ was 122% in 2024.
Foreign investors held about $9.2 trillion of Treasury securities in July 2026, by the Treasury’s estimates. Japan held the most, $1.10 trillion, followed by the United Kingdom with $998 billion. China, with $618 billion, was third.
The verdict: what the evidence shows
Serious, and getting worse. Now about the size of the whole economy, debt held by the public is close to its 1946 record. Under current law the Congressional Budget Office (CBO) projects it at 120% of gross domestic product (GDP) in 2036 and 175% in 2056. Net interest already costs more than defense, and it roughly doubles within ten years. The Treasury calls the path unsustainable.
Both parties built it. Measured against the economy, the debt rose under every president from Reagan to Biden except Clinton. On the official estimate of the 2017 tax act, growth would recover about a quarter of its cost, so the act would not pay for itself. Most of the coming rise in spending, though, is net interest, Social Security and Medicare, under laws already on the books. The best-known claim of a danger line, that growth stalls once debt passes 90% of GDP, did not survive a recheck.
Four claims, against the evidence
Claim“Obama doubled the national debt.”
Partly trueDebt held by the public more than doubled during his presidency, but gross debt rose 88%. Against the economy, gross debt rose 22.2 points under Obama and 27.3 under G.W. Bush, but debt held by the public rose more under Obama.
Claim“Republican tax cuts caused the debt.”
Partly trueThe Bush tax cuts and the 2017 tax act added trillions to deficits. But the debt also grew with recessions, wars and spending laws, under presidents of both parties.
Claim“Tax cuts pay for themselves through growth.”
Not on the official estimateThe Joint Committee on Taxation found that growth would recover $385 billion of the 2017 tax act’s $1.456 trillion conventional cost. That is about a quarter.
Claim“The debt is a spending problem, not a revenue problem.”
Partly trueThe Congressional Budget Office projects revenue just above its 50-year average and spending well above its own, mostly because of net interest, Social Security and Medicare. But tax cuts also cut revenue by trillions.
Download the conclusion
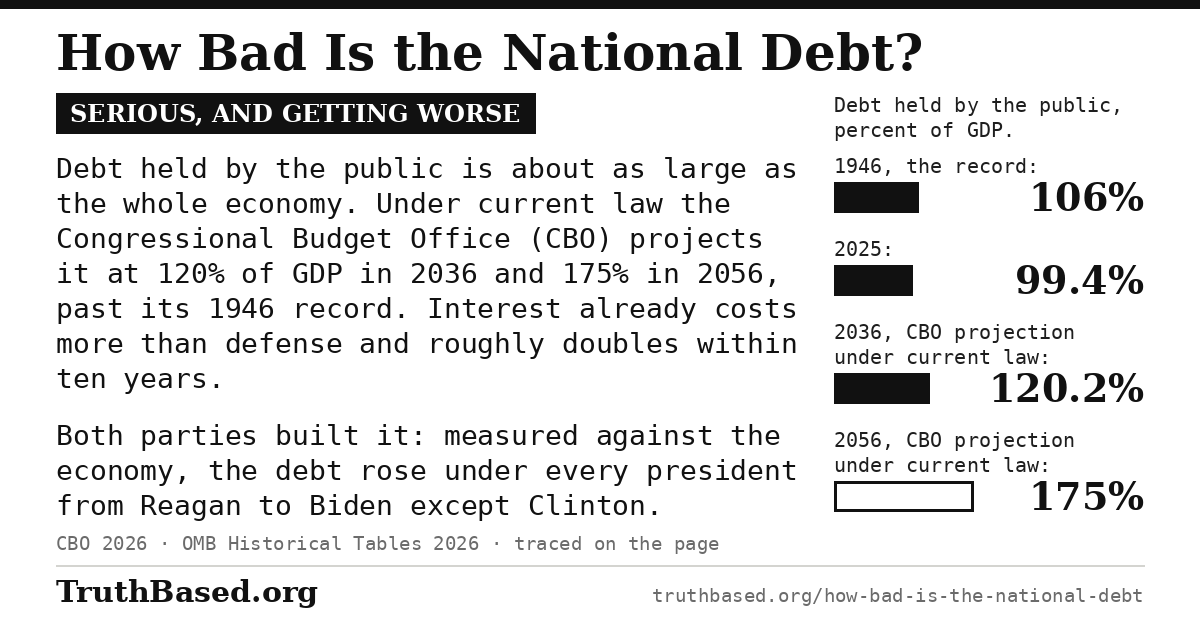
The verdict above as one image, with the figures that frame it: federal debt held by the public as a percentage of GDP. It shows the record of 106% in 1946 and 99.4% in 2025. It also shows the Congressional Budget Office’s projections under current law, 120.2% in 2036 and 175% in 2056. The image is 1,200 by 630 pixels, the size social networks use for link previews, and anyone may download it and post it.
What would change this conclusion
This article concludes that: (1) debt held by the public is about as large as the economy, and under current law the Congressional Budget Office (CBO) projects it to keep rising past its 1946 record; (2) measured against the economy, the debt rose under every president from Reagan to Biden except Clinton; (3) on the official estimate, growth would recover about a quarter of the 2017 tax act’s cost.
These conclusions would be falsified by:
• A CBO baseline in which debt held by the public falls as a share of GDP over the next ten years under current law
• Revised historical tables from the Office of Management and Budget showing the debt ratio falling under another president from Reagan to Biden
• An estimate by the Joint Committee on Taxation or CBO finding that a major tax cut recovered most of its conventional cost through growth
Sources
Office of Management and Budget. Historical Tables, Budget of the U.S. Government, Fiscal Year 2027. April 2026. Tables 1.1, 1.2, 3.1, 7.1, 7.3, 8.1 and 8.4. Source for the table of debt by administration (gross federal debt as a percentage of GDP, debt held by the public, and average deficits, computed from the tables’ dollars), the change in debt held by the public as a percentage of GDP under each president, mandatory spending and net interest in fiscal 2025, net interest, defense and Medicare outlays, revenue and defense as shares of GDP in 1993 to 2001, the largest deficits since 1930, the surpluses since 1969, the fiscal 2009 deficit, and the 90 changes to the debt limit since 1960. whitehouse.gov
Congressional Budget Office. The Budget and Economic Outlook: 2026 to 2036. Testimony of Phillip L. Swagel, Director, before the Subcommittee on Fiscal Responsibility and Economic Growth, Senate Committee on Finance, March 11, 2026. Source for the projections of debt held by the public (101% of GDP in 2026, 120% in 2036, 175% two decades later), the 1946 record of 106%, the 50-year averages of debt, deficits, revenue and spending, the deficit and net interest in 2026 and 2036, the projected rise in spending and its causes, and the 2025 values plotted in the chart. The link is to the committee’s copy. finance.senate.gov
U.S. Department of the Treasury, Bureau of the Fiscal Service. Debt to the Penny. Fiscal Data. Source for gross debt and debt held by the public on September 30, 2026, the first day gross debt passed $40 trillion (August 18, 2026), and the debt on January 20, 2009 and January 20, 2017. fiscaldata.treasury.gov
U.S. Department of the Treasury. America’s Finance Guide: National Debt; Federal Spending. Fiscal Data. Source for the definitions of the deficit, the debt and intragovernmental debt, and of mandatory and discretionary spending. fiscaldata.treasury.gov
U.S. General Accounting Office. Budget Issues: An Overview of Federal Debt. Testimony GAO/T-AIMD-98-221, June 24, 1998. Source for the description of debt held by the public as the measure that “best represents the cumulative effect of past federal borrowing on the economy”. govinfo.gov
U.S. Department of the Treasury. Debt Limit. Source for what the debt limit does and the words “does not authorize new spending commitments”. home.treasury.gov
U.S. House of Representatives, Office of the Historian. Party Government Since 1857. Source for which party held the House and Senate in each Congress from 1981 to 2025, including the change of Senate control in June 2001 and November 2002. history.house.gov
National Bureau of Economic Research. US Business Cycle Expansions and Contractions. Source for the dates of the 2001, 2007–09 and 2020 recessions, and for the 2007–09 recession being the longest since 1945. nber.org
Watson School of International and Public Affairs, Brown University. Costs of War: Findings. Source for the cost of the post-9/11 wars, about $8 trillion, not counting future interest. costsofwar.watson.brown.edu
National Archives. The Constitution of the United States: A Transcription. Source for Article I, Section 9: “No Money shall be drawn from the Treasury, but in Consequence of Appropriations made by Law”. archives.gov
U.S. Senate. Roll call votes: 103rd Congress, 1st session, No. 247 (1993); 107th, 1st, No. 170 (2001); 108th, 1st, No. 196 (2003); 110th, 2nd, No. 213 (2008); 111th, 1st, No. 64 (2009); 115th, 1st, No. 323 (2017); 116th, 2nd, No. 80 (2020); 117th, 1st, No. 110 and No. 314 (2021). Source for the Senate votes and their party breakdowns. The 2008 vote is linked. senate.gov
U.S. House of Representatives, Office of the Clerk. Roll calls 406 (1993), 699 (2017) and 72 (2021). Source for the House votes on the 1993 budget act, the 2017 tax act and the American Rescue Plan, and for no votes from the other party on each. The 2017 vote is linked. clerk.house.gov
Public Laws 103-66 (Omnibus Budget Reconciliation Act of 1993), 110-343 (Emergency Economic Stabilization Act of 2008), 111-5 (American Recovery and Reinvestment Act of 2009), 111-8 (Omnibus Appropriations Act, 2009), 111-148 (Patient Protection and Affordable Care Act), 115-31 (Consolidated Appropriations Act, 2017) and 119-4 (Full-Year Continuing Appropriations and Extensions Act, 2025). Government Publishing Office. Source for the 1993 act’s 36% and 39.6% brackets, the dates the bank rescue, the Recovery Act and the 2009, 2017 and 2025 appropriations acts became law, and the Affordable Care Act’s Medicaid expansion and premium tax credits. The Affordable Care Act is linked. govinfo.gov
Congressional Research Service. The Reconciliation Process: Frequently Asked Questions. Report R48444, by Tori Gorman. March 6, 2025. Source for what reconciliation is: an expedited process in which debate in the Senate is limited, so reaching a final vote needs no three-fifths majority. congress.gov
Joint Committee on Taxation. Macroeconomic Analysis of the Conference Agreement for H.R. 1, the “Tax Cuts and Jobs Act”. JCX-69-17, December 22, 2017. Source for the 2017 act’s conventional cost of $1,456 billion over 2018 to 2027, its effect of about 0.7% on GDP, the $451 billion revenue gain, the $66 billion in added interest and the net $385 billion. jct.gov
Tax Foundation. CBO Figures Dispel Myth that Bush Tax Cuts Caused Today’s Deficit. June 15, 2011. Source for the Tax Foundation’s reading of a CBO review: the tax cuts of 2001, 2003 and 2004 added about $1.8 trillion to deficits over 2002 to 2011, interest included. taxfoundation.org
Tax Foundation. About Us. Source for what the Tax Foundation is: a nonprofit that produces research and analysis on tax policy. taxfoundation.org
Committee for a Responsible Federal Budget. Tax Cut Extensions Would Add $37 Trillion to Debt by 2054. March 24, 2025. Source for the estimate, from CBO’s analysis, that extending the 2017 tax cuts would add about $37 trillion to the debt by 2054. crfb.org
Committee for a Responsible Federal Budget. Unpaid-for TCJA Extension Would Shrink the Economy, CBO Says. April 8, 2025. Source for CBO’s finding, as this report gives it, that the extension would add to growth at first, subtract from it from 2028 and leave the economy smaller from 2034. crfb.org
Committee for a Responsible Federal Budget. About Us. Source for what the committee is: a nonprofit whose leadership includes past heads of the House and Senate Budget Committees and of the Congressional Budget Office. crfb.org
Blanchard OJ, Leigh D. Growth Forecast Errors and Fiscal Multipliers. NBER Working Paper 18779, February 2013. Source for the crisis dated from 2009, the main sample of 26 European economies’ plans for 2010 and 2011, the finding that stronger planned fiscal consolidation went with lower growth than expected, and its reading as higher fiscal multipliers. nber.org
Herndon T, Ash M, Pollin R. Does High Public Debt Consistently Stifle Economic Growth? A Critique of Reinhart and Rogoff. Political Economy Research Institute, Working Paper 322, April 2013. Source for Reinhart and Rogoff’s published −0.1%, the errors found, the corrected 2.2% across 20 advanced economies, and the finding’s “significant support for the austerity agenda”. peri.umass.edu
Reinhart CM, Rogoff KS. Response to Herndon, Ash and Pollin. April 16, 2013, published by the Institute for New Economic Thinking. Source for their acknowledgement of the coding error, their view that it did not affect the paper’s “central message” in any significant way, and their dispute of the charges of selective exclusion and unconventional weighting. ineteconomics.org
International Monetary Fund. World Economic Outlook database, general government gross debt (percent of GDP). Source for Japan’s gross government debt above 200% of GDP since 2013, and for the United States’ 122% in 2024 on the same measure. The figures are from the IMF’s data service; the link is to Japan’s series. api.imf.org
U.S. Department of the Treasury. Executive Summary to the FY 2025 Financial Report of the United States Government. March 2026. Source for the 75-year gap of $79.6 trillion in present value, the words “current policy is unsustainable”, and assets of $6.1 trillion against liabilities of $47.8 trillion. fiscal.treasury.gov
U.S. Department of the Treasury. Notes to the FY 2025 Financial Statements, Note 24: Long-Term Fiscal Projections. Financial Report of the United States Government. Source for what a present value is: future amounts are reduced using an assumed interest rate, because a dollar paid or collected in the future is worth less than a dollar today, which could be invested and earn interest. fiscal.treasury.gov
U.S. Department of the Treasury. Treasury International Capital System, Table 5: Major Foreign Holders of Treasury Securities. Source for foreign holdings of about $9.2 trillion in July 2026, and for Japan’s, the United Kingdom’s and China’s holdings. ticdata.treasury.gov
Cite this article
TruthBased.org. “How Bad Is the National Debt?” Updated November 2026. https://www.truthbased.org/how-bad-is-the-national-debt